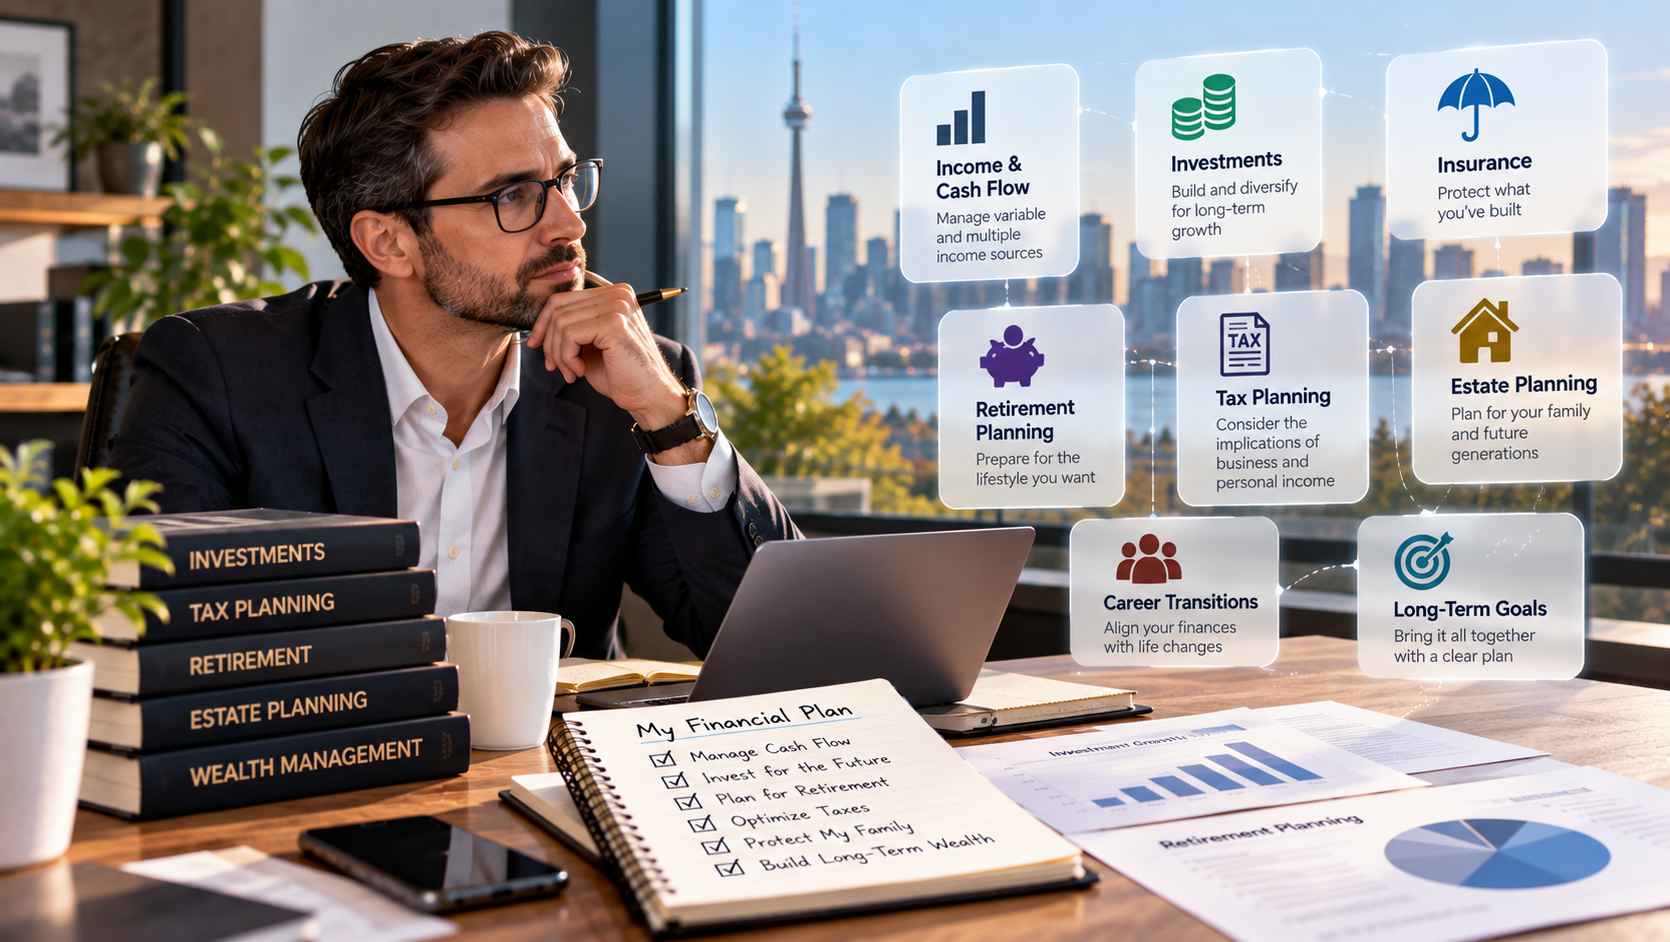

Professionals rarely have perfectly predictable financial lives. Income can change with promotions, bonuses, commissions, partnership interests, consulting work, business ownership, or career transitions. At the same time, decisions about retirement savings, investments, insurance, taxes, and estate planning can become increasingly interconnected.
The more moving parts there are, the harder it can be to evaluate each financial decision on its own.
A professional with an incorporated business, for example, may need to think about both personal income and the finances of the company. Someone with a demanding career may be balancing retirement savings with a mortgage, education costs, investment goals, and family responsibilities.
A coordinated financial plan can provide a framework for considering these priorities together rather than treating them as unrelated decisions.
Why Professionals Often Have More Than One Financial Priority
Financial planning becomes more complicated when income and responsibilities increase.
Early in a career, the main focus may be building an emergency fund and starting retirement savings. Later, the same person may have investments, insurance policies, real estate, business interests, multiple income sources, and estate-planning considerations.
These decisions can affect one another.
Increasing retirement contributions can affect available cash flow. Purchasing a property can change liquidity. Starting a business can introduce new financial risks. A career change can alter income and benefits.
Exponent Investment Management works with professionals and families on wealth management and financial planning, providing an example of how broader financial decisions can be considered as part of a coordinated planning process.
The objective is not to make every decision at once. It is to understand how individual choices fit into larger financial goals.
Managing Income and Cash Flow
Professionals with variable or multiple sources of income may need to think differently about cash flow than someone receiving a predictable salary.
Bonuses, commissions, partnership distributions, consulting income, dividends, or business income can create periods of higher and lower cash flow.
That can make it tempting to make financial decisions based on the income available at a particular moment.
A broader view considers both current needs and longer-term objectives.
Questions might include how much cash should remain readily available, how much should be directed toward longer-term savings, and how much flexibility is needed for major upcoming expenses.
For incorporated professionals, personal and business cash flow should also be considered separately. Business funds may serve operational purposes and should not automatically be treated as personal spending or investment capital.
Understanding the distinction can help provide a clearer picture of what resources are genuinely available for personal goals.
Retirement Planning Beyond a Single Account
Retirement planning is not simply a matter of contributing to one investment account.
Professionals may eventually rely on several sources of income, including registered savings, non-registered investments, pensions, government benefits, real estate, or income from a business.
The timing of retirement can also change the picture.
Someone planning to retire at 55 has a different planning horizon from someone expecting to work until 70. A professional who wants to reduce working hours gradually may have different income requirements from someone planning a complete career transition.
The Government of Canada’s financial planning guidance emphasizes defining personal goals, considering future needs, and looking at areas such as investments, insurance, taxes, and estate planning as parts of a broader financial plan.
Government of Canada financial planning guidance
The important point is that retirement planning should reflect the person’s expected lifestyle and overall financial position rather than focusing on one savings account in isolation.
Tax and Insurance Considerations
Taxes can become more complicated as income sources multiply.
Employment income, business income, investment income, and other forms of compensation may each have different implications. For professionals with corporations or partnerships, decisions about how money moves between the business and the individual can also require specialized tax advice.
Financial planning does not replace professional tax advice, but it can help ensure tax considerations are included when broader decisions are being made.
Insurance is another area that can become more important as income and responsibilities increase.
A professional may have a larger mortgage, dependents, business obligations, or income that would be difficult for the household to replace. Insurance needs can therefore change over time.
Rather than viewing insurance as a standalone product decision, it can be considered alongside income, assets, debt, family responsibilities, and long-term goals.
Estate and Wealth Transfer Planning
Estate planning is sometimes postponed because it feels relevant only much later in life. For professionals with substantial assets or complicated financial arrangements, however, it can become an important part of financial organization.
An estate plan can address how assets should be handled, who should make financial or legal decisions if the individual becomes unable to do so, and how wealth should eventually be transferred.
Business owners may also have additional considerations involving ownership interests, shareholder arrangements, or succession.
The exact legal and tax implications depend on the person’s circumstances and province or territory, so estate planning generally requires coordination with appropriate legal and tax professionals.
The broader financial plan should account for these conversations rather than treating them as completely separate from retirement and investment planning.
Reviewing the Plan as Life Changes
A financial plan should not be treated as a document that is created once and forgotten.
Professionals can experience significant changes over the course of a career. They may change employers, become partners, start a business, sell an investment property, receive an inheritance, have children, relocate, or decide to retire earlier or later than expected.
Each change can affect other parts of the financial picture.
For example, a new business opportunity may create the potential for additional income but also increase concentration and reduce available liquidity. A career transition might change pension benefits or alter the amount available for retirement savings.
Regular reviews allow the financial plan to evolve alongside those changes.
When Coordinated Advice Can Help
The value of professional financial planning is often less about finding one perfect financial product and more about coordinating several decisions.
A coordinated wealth planning approach can bring together questions about cash flow, investments, retirement, taxes, insurance, estate planning, and long-term goals.
This can be particularly useful for professionals whose financial lives have become more complex through career progression, incorporated businesses, multiple income sources, or significant accumulated assets.
The process should still be collaborative. The professional provides the goals, priorities, circumstances, and decisions, while qualified advisors can help explain available strategies and their potential implications.
Different specialists may also need to be involved. Financial planners, investment professionals, accountants, tax advisors, insurance professionals, and lawyers can each contribute expertise to different parts of the overall picture.
Keeping the Financial Picture Connected
Complex finances do not necessarily require complicated decisions at every step. They do, however, benefit from context.
A retirement decision can affect investment needs. A business decision can affect personal cash flow. An estate decision can affect ownership and tax considerations. Insurance needs can change as family responsibilities and assets grow.
Looking at these relationships can make it easier to identify gaps and competing priorities.
For professionals with changing income and multiple financial objectives, the goal of planning is not to predict every future event. It is to create a flexible framework that can be reviewed and adjusted as circumstances change.
That broader perspective can help turn a collection of financial decisions into a more coherent long-term plan.